
Quick answer
GPS and BLE tags speed up the year-end audit by sending count teams straight to each asset’s last known location and flagging exceptions, including ghost assets, before reconciliation. Match every tracker to an asset record, check location timestamps, verify the equipment in person, and investigate every difference. Accounting approvals and valuation stay in your financial systems.
Stanford’s property manual sets a 98 percent physical inventory accuracy goal for its departments and says that target conforms to current industry standards for property management. Federal agencies must count capitalized assets once a year under the Federal Personal Property Management Act of 2018.
Manufacturers, contractors, and fleet operators set their own targets, and 98 percent is a demanding one. Your count slows down every time equipment moves between jobsites, yards, or service vans without a matching record update. A register alone does not tell your team which jobsite, service bay, or production line to search.
Hitting an accuracy target takes more than finding equipment. Your team has to locate each asset, confirm its identity, and resolve every difference before the count closes.
What is fixed asset tracking?
Fixed asset tracking, also called capital asset tracking, ties durable business equipment to its identity, assigned location, custodian, and movement history. That equipment is the property, plant, and equipment (PP&E) your balance sheet reports. For operations teams, it means knowing where an excavator, service trailer, diagnostic device, or production tool belongs and where it was last seen.
Finance needs a dependable equipment record. Operations needs current location evidence. Connect the two, and your team stops starting every search from a blank count sheet.
Register versus physical inventory: what each one proves
A fixed asset register records what your organization recognizes and manages as assets. Typical fields include acquisition details, ownership, assigned location, and depreciation, as your accounting policy defines them.
A physical inventory checks real equipment against those records. GPS and BLE observations point the count team in the right direction. A location message alone does not establish ownership, condition, or accounting value.
| Evidence source | What it establishes | What still needs verification |
|---|---|---|
| Fixed asset register | Recorded identity, assignment, and accounting information | Whether the equipment is present and correctly recorded |
| GPS or BLE observation | Where and when an associated tracker was detected | Asset identity, attachment, condition, and record accuracy |
| Physical inspection | Observed equipment, identifying details, and condition | Accounting treatment and approval of record changes |
Where year-end asset counts break down
- Transfers outpace record updates. A generator moves from a construction site to a repair shop, but its register location never changes. Count teams search the wrong site, call supervisors, and start over somewhere else. Record every transfer when it happens, with the destination and the responsible custodian, so the chain of custody holds up at count time.
- Tracker identity drifts from equipment identity. A tag moves to replacement equipment without an updated association. The location feed still looks active, but it points to the wrong asset record. Check the equipment identifier against the attached tracker before you accept the observation.
- Stale observations look current. A map marker without a visible timestamp creates false confidence. Equipment last detected before a transfer still shows at its old location. Put observation age on every count worksheet and route stale records for investigation.
- Ghost assets inflate the register when disposals and repairs stay open. Equipment scrapped, lost, or sent offsite stays on the count list with no supporting documents. When property tax and insurance schedules draw from the register, you keep paying for equipment you no longer have. Split repair, transfer, disposal, and unexplained absence into separate exception categories, each with an owner and a documented resolution.
- Idle equipment triggers duplicate purchases. A unit sitting unrecorded at the back of a yard looks like a shortage, so someone buys another one. Check location history and inventory tracking records for equipment you already own before a capital request goes out.
- Manual counts pull skilled people off the job. Freezing yard movements, pausing a line, or sending technicians to walk a facility with a clipboard costs production and billable hours. Location-guided searches send counters to the right area instead of a full sweep.
- Labels fail where the equipment works. Paint, grease, abrasion, and enclosures cover barcodes and serial plates on heavy equipment, and every unreadable label becomes a manual lookup. BLE tags report by radio, so a tag mounted out of view still reports when a gateway is in range. Test tag placement on metal equipment before rollout.
- Offsite custody hides equipment at cutoff. Tools and diagnostic kits sit in locked service vans, subcontractor yards, and remote jobsites that count teams cannot reach before cutoff. GPS shows which site holds the equipment, and BLE gateways in vehicles report the tagged tools riding with them.
Phase 1: Define the count and cutoff
What is a year-end physical inventory count, and why is it required?
A year-end physical inventory count verifies equipment against records at a defined reporting cutoff. It gives finance the evidence to investigate missing assets, wrong locations, unrecorded equipment, and open disposals.
The requirement comes from the rules that govern your organization, your funding, and your internal policies. Another institution’s schedule or capitalization threshold is not a universal rule for your business.
How often does a company or government agency have to count its fixed assets?
Count frequency depends on your policy and funding terms. Indiana University’s fiscal guidance, referencing OMB Uniform Guidance, requires a physical inventory of equipment reconciled with records at least once every two years. Any differences must be investigated to find the cause.
Where your policy allows it, cycle counting by site or asset class spreads verification across the year, so the formal count confirms records instead of rebuilding them.
Have finance confirm the controlling schedule before you plan fieldwork. Then define the asset population, cutoff, locations, responsible staff, and the evidence required to close the count.
- Agree which owned, leased, loaned, and offsite equipment is in scope under your policy.
- Lock the register version used for the count.
- Document how transfers during the count get recorded.
- Assign each site and exception category to a named owner.
Phase 2: Match GPS and BLE to equipment
Can GPS or BLE trackers be used for fixed asset tracking?
Yes. GPS asset tracking points teams to equipment that moves between outdoor sites. Bluetooth Low Energy (BLE) tags report through compatible GPX trackers or gateways in range, which speeds up searches for tools and equipment inside facilities.
GPX enterprise asset tracking software brings AI-powered asset tracking into your operational workflows. It integrates with ERP, WMS, and TMS systems, while your accounting system keeps the financial records and approval controls.
For tagged equipment, AssetTag Pro hangs, sticks, or screws onto an asset. It ships activated with no app pairing and reports through a GPX tracker or gateway in range. BLE RoadWired pairs a hardwired vehicle GPS tracker with a mobile BLE gateway, so vehicles and forklifts pick up nearby tagged equipment as they move. Together, those gateways give you automated discovery of tagged equipment along routes your fleet already drives.
Test detection in your actual operating area before you build count assignments on it. Shelving, equipment placement, travel routes, and gateway coverage all shape where observations come from. Treat a missing observation as a reason to investigate, not proof that an asset is gone.
How do barcodes, RFID, BLE, and GPS compare for fixed asset tracking?
Each method answers a different evidence question. Barcodes and QR labels confirm identity when a counter scans them, but they need line of sight and a person standing at the asset. Passive RFID reads tags without direct line of sight, through handheld or fixed readers brought close to the equipment. BLE tags broadcast on their own, so a compatible tracker or gateway in range reports them without anyone walking the aisle. GPS reports outdoor position for equipment that moves between sites.
Use barcodes or RFID for deliberate identifier checks, BLE for tagged equipment inside facilities and vehicles, and GPS for outdoor movement. Pair location observations with identifier checks whenever the count requires proof of the actual equipment.
Phase 3: Verify assets and investigate differences
How do you conduct a fixed asset audit?
Start with a controlled register, organize your location evidence, and verify equipment against the count instructions. Finish with fixed asset reconciliation, and keep the operational inventory separate from the auditor’s independent procedures and conclusions.
- Match identifiers. Tie each tracker to its asset number and equipment serial number. Fix duplicate or incomplete associations before fieldwork starts.
- Prepare location evidence. Record the latest observation, timestamp, assigned site, and custodian. Flag stale observations instead of presenting them as current positions.
- Verify registered equipment. Find the listed asset, confirm its identifying details, and note any condition or assignment differences.
- Identify zombie assets. Walk the operating area for unrecorded equipment: physical assets missing from the fixed asset register. Confirm ownership and recording status before you add them.
- Reconcile and approve. Document findings, attach supporting evidence, and route proposed changes through your established approval process.
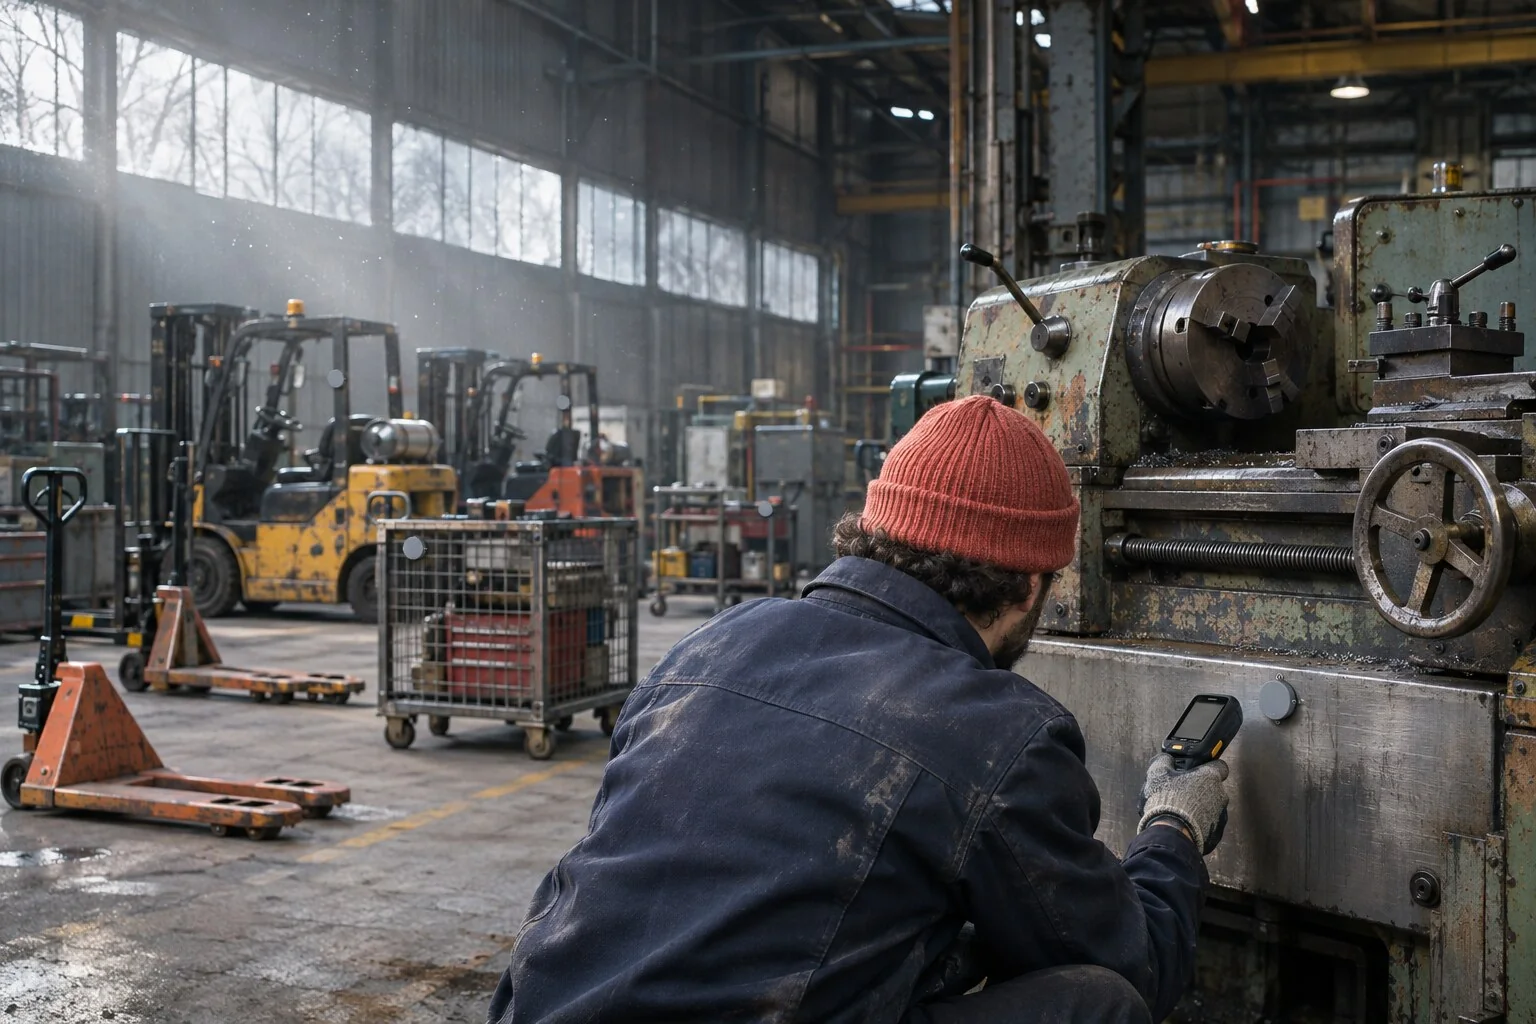
At a manufacturing plant, a BLE observation sends the team to the right production area. The counter then checks the equipment identifier. At an outdoor equipment yard, a GPS observation narrows the search before the same verification step.
Resolve register-to-floor discrepancies by category
Classify the discrepancy before you change the record. A wrong location, duplicate entry, unrecorded transfer, detached tag, and unexplained absence each call for a different action.
Assign an owner, preserve the original observation, and collect supporting documents. Finance approves accounting changes after the investigation; operations corrects custody and movement records through its own controls.
A missing signal never justifies an automatic write-off. An active signal does not close an exception either when the tracker sits on different equipment.
Phase 4: Measure fixed asset reconciliation speed and audit ROI
How long does a manual fixed asset count take compared to an automated one?
No universal duration holds up for either method. Site access, asset dispersion, identifier quality, equipment movement, and reconciliation requirements set the workload.
GPS and BLE shorten the search stage by giving count teams a location-based starting point. Identifier checks, condition review, exception investigation, and approval still happen.
Measure each activity separately during a pilot. Track search time, verification time, open exceptions, and reconciliation effort for comparable equipment groups. Keep setup and tagging work apart from recurring count effort.
Build the audit ROI case from figures your own pilot produces: search hours removed, exceptions closed before cutoff, staff hours returned to production, and duplicate purchases avoided when idle equipment turns up. Judge the result by completed, supported records. A faster walkthrough that leaves an open exception queue has not finished the job.
What comes next for audit evidence?
The shift from passive tracking to agentic asset intelligence moves exception review into the months between formal counts, which is what continuous audit readiness looks like in practice. Transfers, long idle periods, and unexpected movement trigger an investigation while the equipment’s history is still easy to reconstruct.
Scout AI, GPX’s conversational supply-chain analyst, answers natural-language questions over location and IoT data. Ask “Which assets have been idle for more than 48 hours?” and your team has a targeted check list before count assignments go out, the same idle-equipment question an equipment utilization report tracks over time.
Financial decisions stay with people. AI asset intelligence points attention at unusual activity; the responsible team verifies the equipment and authorizes record changes.
When GPX Is Not the Right Fit
GPX serves enterprise operations and businesses tracking 10+ high-value assets. A single tracker, a family car, or a pet fits a consumer product better, such as GPX’s sister brand Logistimatics or Apple AirTag.
GPX is not a dashcam, a driver-behavior product, or an ERP. Run it for asset and supply-chain visibility alongside the systems that own accounting and other business controls.
Pick Your Pilot Sites Before the Next Count Cutoff
Start where count teams lose the most time: yards full of mobile equipment, facilities with dispersed tools, and service vans that leave before cutoff. On those sites, ask every vendor to prove the workflow connects equipment identity, timestamped location evidence, and a clear exception queue without weakening verification or approval.
Talk to the GPX team about a pilot built on your actual sites and your count process.
Frequently Asked Questions (FAQs)
How does BLE asset tracking compare to passive RFID and barcodes for year-end audits?
BLE tags report on their own whenever a compatible tracker or gateway is in range, so count teams know where to look before fieldwork starts. Passive RFID and barcodes respond only when a reader or scanner comes close to the asset. For the audit, use BLE to locate equipment and a barcode or serial number check to prove identity.
Should every piece of equipment use the same tracker?
No. Match the device to movement patterns, operating conditions, and detection coverage. Outdoor mobile equipment and indoor tools have different tracking needs, even when both sit in the same register.
Does GPX replace the fixed asset register?
No. GPX supplies location intelligence and integrates with ERP, WMS, and TMS systems. Your accounting or asset-management system keeps the authoritative financial records and approval process.
How long does an AssetTag Pro battery last between counts?
AssetTag Pro runs on a single replaceable CR2477 coin cell, and battery life depends on how often it reports. Your team swaps the cell instead of retiring the tag, so the tracker-to-asset association stays intact across counts.
How do GPS and BLE trackers help eliminate ghost assets before the year-end audit?
Trackers surface ghost asset candidates months before cutoff. A register record whose tag has stopped reporting, or whose tracker sits on different equipment, moves into the exception queue early. Scout AI lets your team ask which tagged assets have not reported recently; your count team verifies each one, and finance approves any retirement.