
Rising commercial fleet insurance premiums land on your renewal every year, and most underwriters reject a hardware invoice as proof of anything. You still cut what you pay with tracking hardware, and the size of the credit depends on the policy type, not the device brand. GPX Intelligence builds AI-powered multi-sensor trackers and AssetTag hardware for theft recovery, and operators use that data to negotiate inland marine and equipment rates with their underwriters.
Fleet risk management programs built on driver-behavior data publish the clearest numbers in the market. Travelers advertises a premium reduction of up to 15 percent on certain commercial auto liability premiums for qualifying businesses that share telematics data, and Nationwide publishes a 10 percent commercial auto credit on select coverages through Vantage 360 Fleet. Earning either credit means knowing what your hardware monitors and handing your broker the right history.
| Platform or Tool Type | What It Monitors | Policy It Supports | Best Fit |
|---|---|---|---|
| GPX Intelligence | Asset location and theft recovery across cellular, BLE, GPS, satellite, and WiFi positioning | Inland marine and contractor equipment | Universal asset & fleet tracking across 50+ industries |
| Driver-behavior telematics programs | Hard braking, acceleration, cornering, speed, and mileage | Commercial auto liability | Carrier credit programs from Progressive, Travelers, and Nationwide |
| Electronic logging devices | Hours of service and engine data | Commercial auto and trucking | DOT compliance and carrier ELD-sharing programs |
| Dashcams | Road-facing and cab-facing video | Commercial auto liability | Claims defense and driver coaching |
| Logistimatics | Single-vehicle and personal GPS location | Personal auto and small business auto | Consumers and SMB operators |
Why Most Operators Get Denied
Plenty of fleet managers assume any tracking device buys a lower premium. Commercial underwriting does not work that way. Five mistakes block most credits.
- Confusing commercial auto with equipment coverage. Brokers classify moving vehicles differently than stationary assets. A list of tracked trailers means nothing to an underwriter pricing driver liability. Your data has to match the risk on the policy you are negotiating.
- Relying on personal policy precedents. Managers point to consumer anti-theft rules and expect the same treatment. Personal-auto anti-theft discounts required in states like New York cover private passenger vehicles, not commercial fleets. Commercial risk gets priced on your corporate loss data.
- Skipping the asset schedule. Underwriters want proof the devices are installed, active, and watching the exact assets on the schedule. Your broker will not reconcile that for you, so a mismatch between tracker serial numbers and scheduled equipment turns into weeks of back-and-forth and a renewal that closes at standard rates.
- Presenting raw pings instead of alerts. Insurers do not pay for dots on a map. They pay for risk mitigation. An underwriter prices location history that arrives with AI-driven geofence alerts, after-hours movement flags, and recovery logs attached, and sets the same data aside when it is a spreadsheet of coordinates.
- Carrying unrecovered losses into renewal. Repeated equipment or cargo theft that never ends in a recovery pushes carriers toward non-renewal rather than a credit. Documented recoveries reverse that direction.
Commercial Auto Telematics vs. Inland Marine Policies
Start by learning how your carrier categorizes the risk. Commercial auto policies price driver behavior, so underwriters want hard braking, acceleration, and cornering metrics. If your trucks run public highways, the question is how safely your team drives.
Equipment, trailers, and specialized machinery usually sit on inland marine or contractor equipment policies. There the exposure is theft and loss, not collision. Inland marine underwriters skip the driver scorecard and ask one question: “Can you recover a stolen generator before it crosses state lines?”
Any credit for GPS theft protection on an inland marine policy gets negotiated directly with your broker and underwriter. Major carriers do not publish those theft-recovery credits as flat percentages. Match the hardware to the asset class, because a driver-behavior tool will never win an inland marine theft credit.
What the Major Carriers Publish
A handful of carriers put real numbers on their commercial programs. Everything else is negotiated at the desk.
- Progressive Snapshot ProView publishes a minimum 5 percent credit for the initial term, then prices renewal on the driving data it collects.
- Progressive Smart Haul covers commercial truckers who share electronic logging device data, with a published minimum 5 percent credit at enrollment.
- Travelers lists up to 15 percent on certain auto liability premiums, per the trade coverage linked above.
- Nationwide Vantage 360 Fleet carries a published 10 percent commercial auto credit on select coverages. State availability varies, so confirm eligibility before you put the savings in your budget.
- Liberty Mutual and The Hartford both run commercial programs and set credits case by case after reviewing fleet data.
Confirm every figure with the carrier before you renew. Program terms, eligibility, and state availability change from year to year.
Matching Hardware to Asset Class
Coverage arguments get stronger when every asset reports in. GPX builds the network, the sensors, and the Scout AI platform, which puts your whole inventory on one screen. That is a different job than vehicle telematics.
A heavy excavator needs different hardware than a returnable shipping container. High-value machinery takes a ruggedized tracker with continuous location reporting and real durability. AssetTag runs on a replaceable coin-cell battery, so mixed yards put ruggedized units on the earthmovers and small tags on tools and attachments.
Both feed the same control tower. That record proves to an underwriter that you manage inventory actively instead of walking the yard once a week. A tracker mounted to the chassis gives you an exact location history the moment an asset moves after hours.
Live Data from Shipment Sensors
Enterprise operators need data that moves faster than their freight. Stale software creates visibility gaps that cost money and slow recoveries. GPX Smart Labels are peel-and-stick sensors for shipments and pallets, and they feed live data into your supply chain software so you see delays and route deviations as they happen.
For fixed assets, BLE tags build a tight net across indoor facilities and outdoor yards. Scout AI reads the sensor data, predicts where assets should be, and flags anomalies before they become losses. That is the gap between recording a cargo theft and stopping one, and it is the kind of AI risk mitigation an underwriter prices in. When tracking reaches individual shipments, your risk profile improves.
What to Bring to Your Broker
Show up to renewal without organized data and you pay standard market rates. Build the case first. Four documents do most of the work.
First, a complete device list. Map every tracker serial number to the matching VIN or equipment identification number on your asset schedule, line by line, so your broker has nothing left to reconcile.
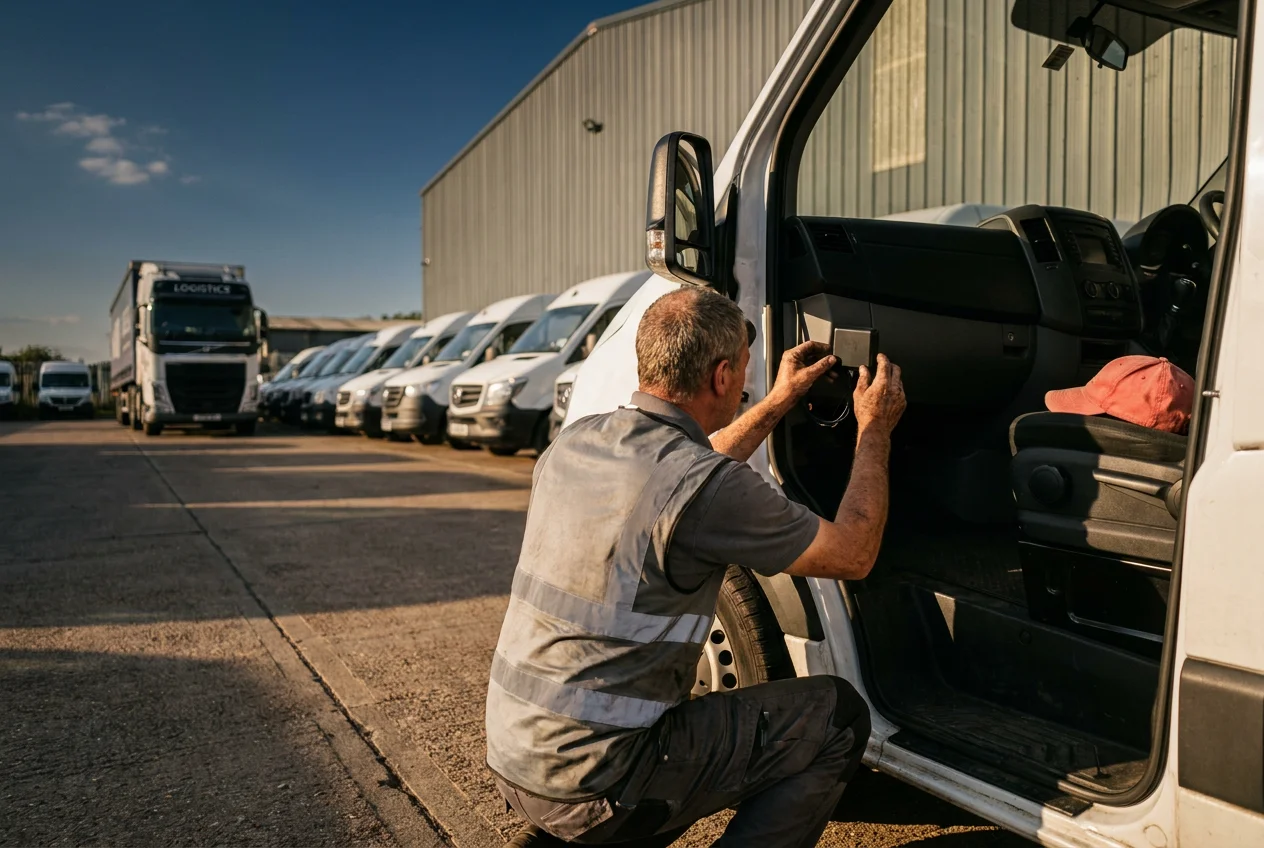
Second, coverage detail on your high-value assets. Call out your most expensive machinery and name the hardware protecting it. If you run passive disabling hardware alongside location sensors, document it, because underwriters reward assets that cannot be hot-wired.
Third, historical recovery records. If your theft recovery devices have found missing equipment, bring the logs. A recovery history proves the system works in the field and answers the loss record that drives non-renewal.
Fourth, your geofence and after-hours alert policy. Show how the system notifies a manager the minute equipment leaves a job site at 2:00 AM. Proactive alerts prove you stop theft in progress instead of counting losses the next morning.
When GPX Is Not the Right Fit
GPX is an enterprise location and theft-recovery platform, not a driver-behavior product. If your only goal is scoring harsh braking, cornering speed, and cab-facing video for a commercial auto policy, buy a different tool. GPX is not a dashcam and not an OBD-II diagnostic suite.
GPX also serves B2B operators running commercial fleets, heavy construction equipment, and multi-site supply chains. One tracker for a teenage driver or a family car is the wrong use case. Consumer options such as Bouncie, or our sibling brand Logistimatics, fit that budget and that policy far better.
Chase the Largest Credit First
Pick the policy with the largest premium and the clearest published program. For most mixed fleets, that means commercial auto credits first and a negotiated theft-recovery credit on equipment second. Work the checklist below before you sign anything.
- Name the policy type. Decide whether you are negotiating commercial auto or inland marine equipment coverage.
- Align hardware to the risk. Driver-behavior telematics wins auto liability credits. Dedicated theft-recovery tracking wins equipment credits.
- Export the asset schedule. Cross-reference active trackers against the machinery listed on your insurance documents.
- Document your operating rules. Print your geofence configurations and alert routing to prove someone watches the data.
- Open the broker negotiation early. Ask about unadvertised theft-protection credits on contractor equipment well before the renewal date.
Protecting physical inventory shows up directly in your premium and your bottom line. See how our AI-powered visibility platform secures high-value assets by exploring our heavy equipment tracking solutions.
Frequently Asked Questions (FAQs)
Does a GPS tracker automatically lower my commercial auto premium?
No. Commercial auto underwriters want driver-behavior telematics data before they issue a credit. Location tracking alone does not qualify for programs like Progressive Snapshot ProView or Nationwide Vantage 360 Fleet.
Can I get a discount for tracking my construction equipment?
Yes. Heavy machinery usually sits on an inland marine or contractor equipment policy. Credits for GPS theft protection on those policies are negotiated with your broker and underwriter based on your hardware and your recovery protocols.
How does AI fleet tracking impact inland marine insurance rates?
Inland marine underwriters price theft and loss exposure, so the value sits in what the AI produces, not in the tracker itself. Scout AI reads sensor data across your assets, predicts where each one should be, and flags after-hours movement as it happens, which gives your broker geofence rules and recovery logs to negotiate against. Credits on these policies stay case by case rather than a published percentage.
What is the average insurance discount for commercial fleets using telematics?
No single industry average exists, because every carrier scores its own program. Published commercial figures run from a minimum 5 percent at enrollment with Progressive Snapshot ProView and Smart Haul, to a 10 percent credit on select Nationwide Vantage 360 Fleet coverages, to up to 15 percent on certain Travelers auto liability premiums. Equipment and inland marine theft credits sit outside those published ranges and get set at the underwriting desk.
What exact data does my insurance broker need?
Start with a device list that ties every tracker serial number to an asset VIN or equipment number on the schedule. Add your geofence rules, after-hours alert policy, and logs from any successful asset recovery.
Does GPX replace my dashcam or ELD?
No. GPX handles asset location, theft recovery, and supply chain visibility. Keep your dashcam and ELD for driver scoring and hours-of-service compliance, then run GPX alongside them for equipment and shipment coverage.